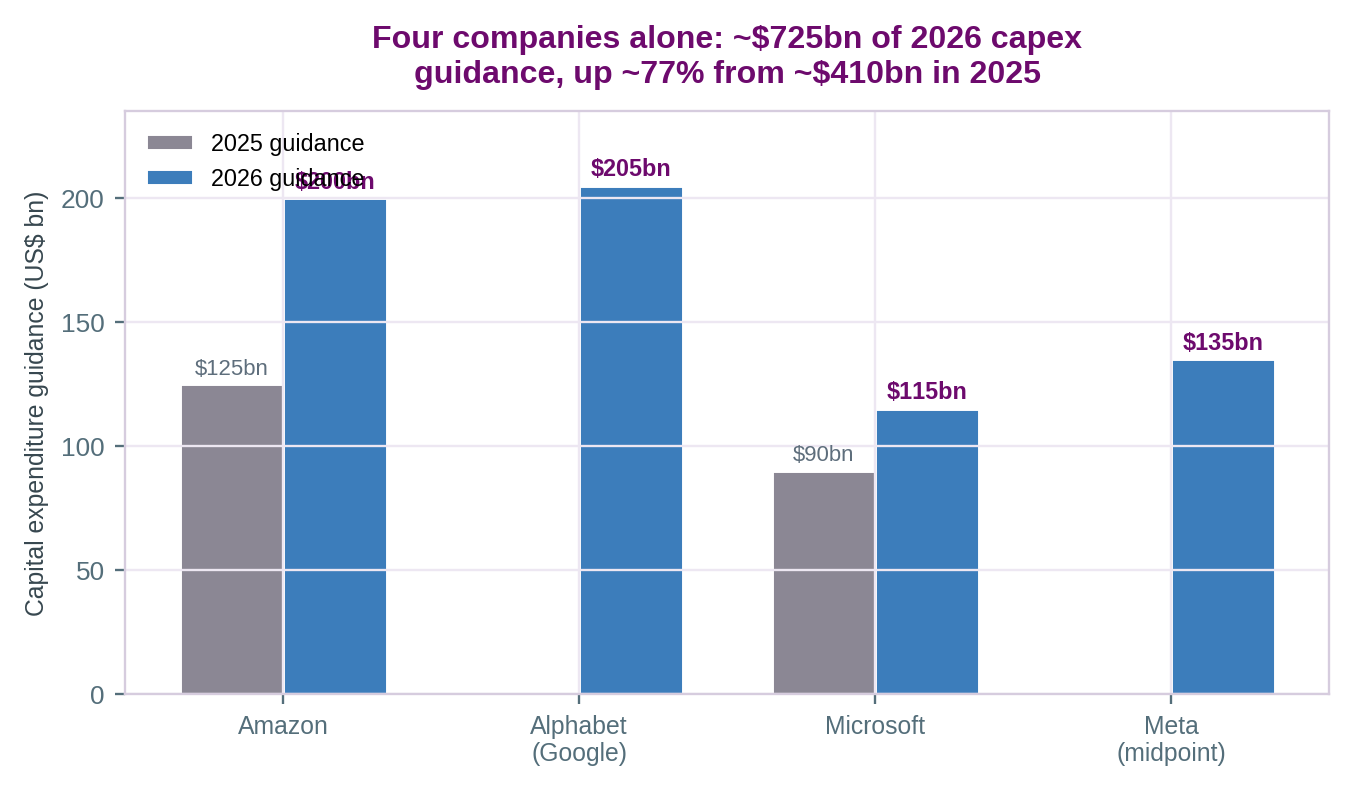
One enormous global demand cycle, three India-specific compute-policy instruments, and India's own physical data-centre build-out are all running underneath this report simultaneously, on largely independent timetables. Conflating them into one "AI opportunity" number is the single easiest way to misread this sector, at either half of the stack.
| Demand cycle | Anchor / driver | What is actually driving it |
|---|---|---|
| 1. Global hyperscaler capex | Microsoft, Amazon, Google, Meta | Combined ~US$725bn 2026 capex guidance, up ~77% from ~US$410bn in 2025 — overwhelmingly earmarked for AI data centres, GPUs and power |
| 2. GPU/HBM physical scarcity | TSMC, Nvidia, SK Hynix, Samsung, Micron | CoWoS advanced-packaging capacity reported "sold out through 2026"; HBM production sold out through 2026-27 under multi-year supply agreements |
| 3. India semiconductor localisation | India Semiconductor Mission 2.0 | $13.5bn outlay, three OSAT/ATMP facilities operational as of this report's research date |
| 4. Sovereign AI compute build-out | IndiaAI Mission | GPU access scaling toward a 100,000-GPU public-access target by December 2026, at a subsidised ~₹65/GPU-hour |
| 5. India IT-hardware manufacturing | IT Hardware PLI 2.0 | ₹17,000cr incentive outlay over six years, covering server manufacturing |
| 6. India's physical data-centre build-out | CBRE/JLL market data | Operational capacity crossed ~1,700MW in 2025; hyperscale pre-committed capacity made up 82% of H1 2026 absorption — demand locked in years ahead of what any operational-MW count shows |
Source: Dart Consultants, compiled from valueaddvc.com/cnbc.com/futurumgroup.com (hyperscaler capex), digitimes.com/tomshardware.com (CoWoS/HBM), ism.gov.in and indiaai.gov.in-linked coverage (ISM 2.0, IndiaAI Mission), india-briefing.com/pib.gov.in (PLI 2.0), and CBRE/JLL India data-centre market research — see Notes for full citation list.
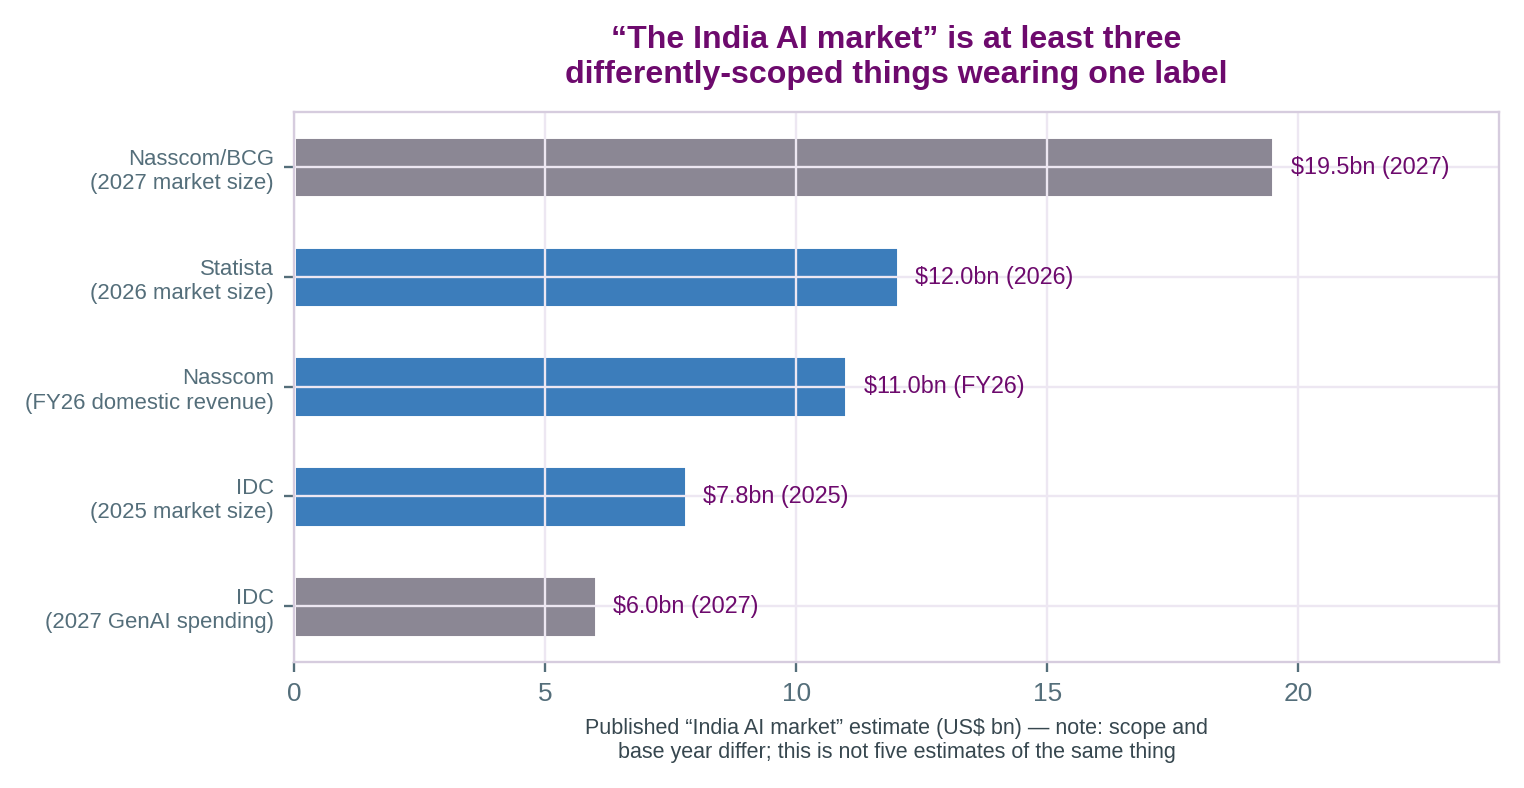
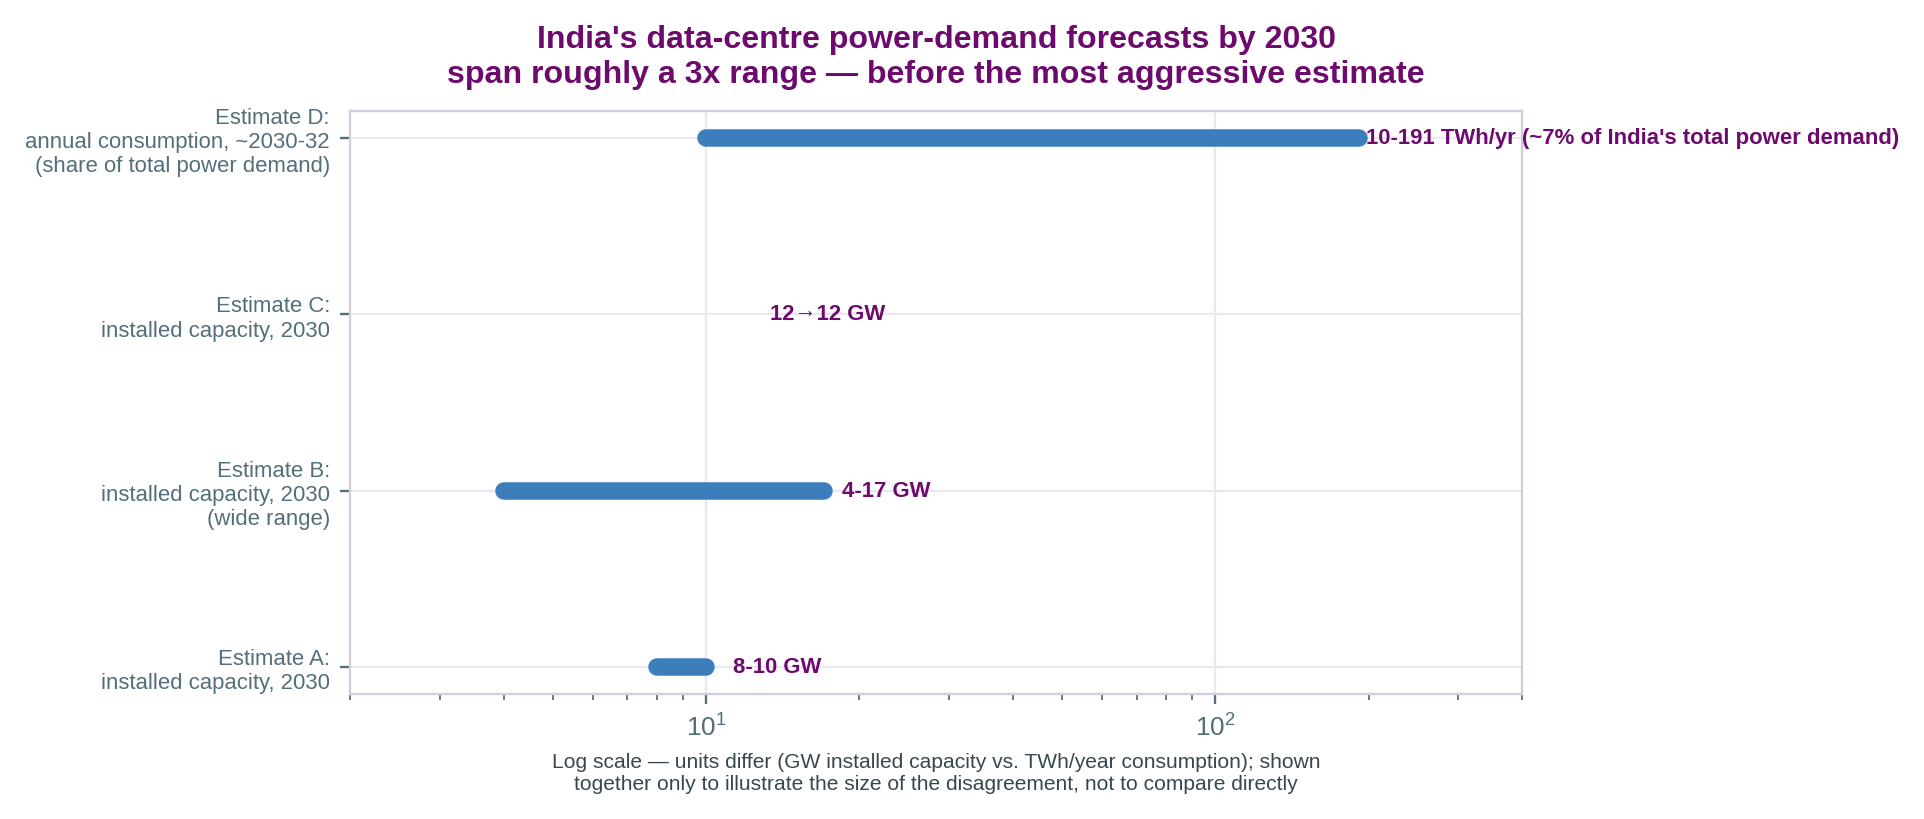
Published "India AI market" figures and India data-centre power-demand forecasts each use different scope, base years and, in the power-demand case, different units entirely (installed GW vs. annual TWh consumption). Five AI-market estimates and four power-demand estimates are shown below; none of the ten converges on a single number, and reporting only the largest or newest without saying so would be exactly the failure mode this report exists to avoid.