Thirty-five NSE/BSE-listed companies touch this stack today, from a ₹12,491 crore pure-play GPU-cloud operator to a ₹11.8 lakh crore telecom major with a single-digit-percent data-centre sliver — a roughly 95x range in scale that, as in every Dart Consultants primer, tells you almost nothing on its own about how much of a company's business is actually AI/data-centre exposure, or how exposed its valuation already is to that story.
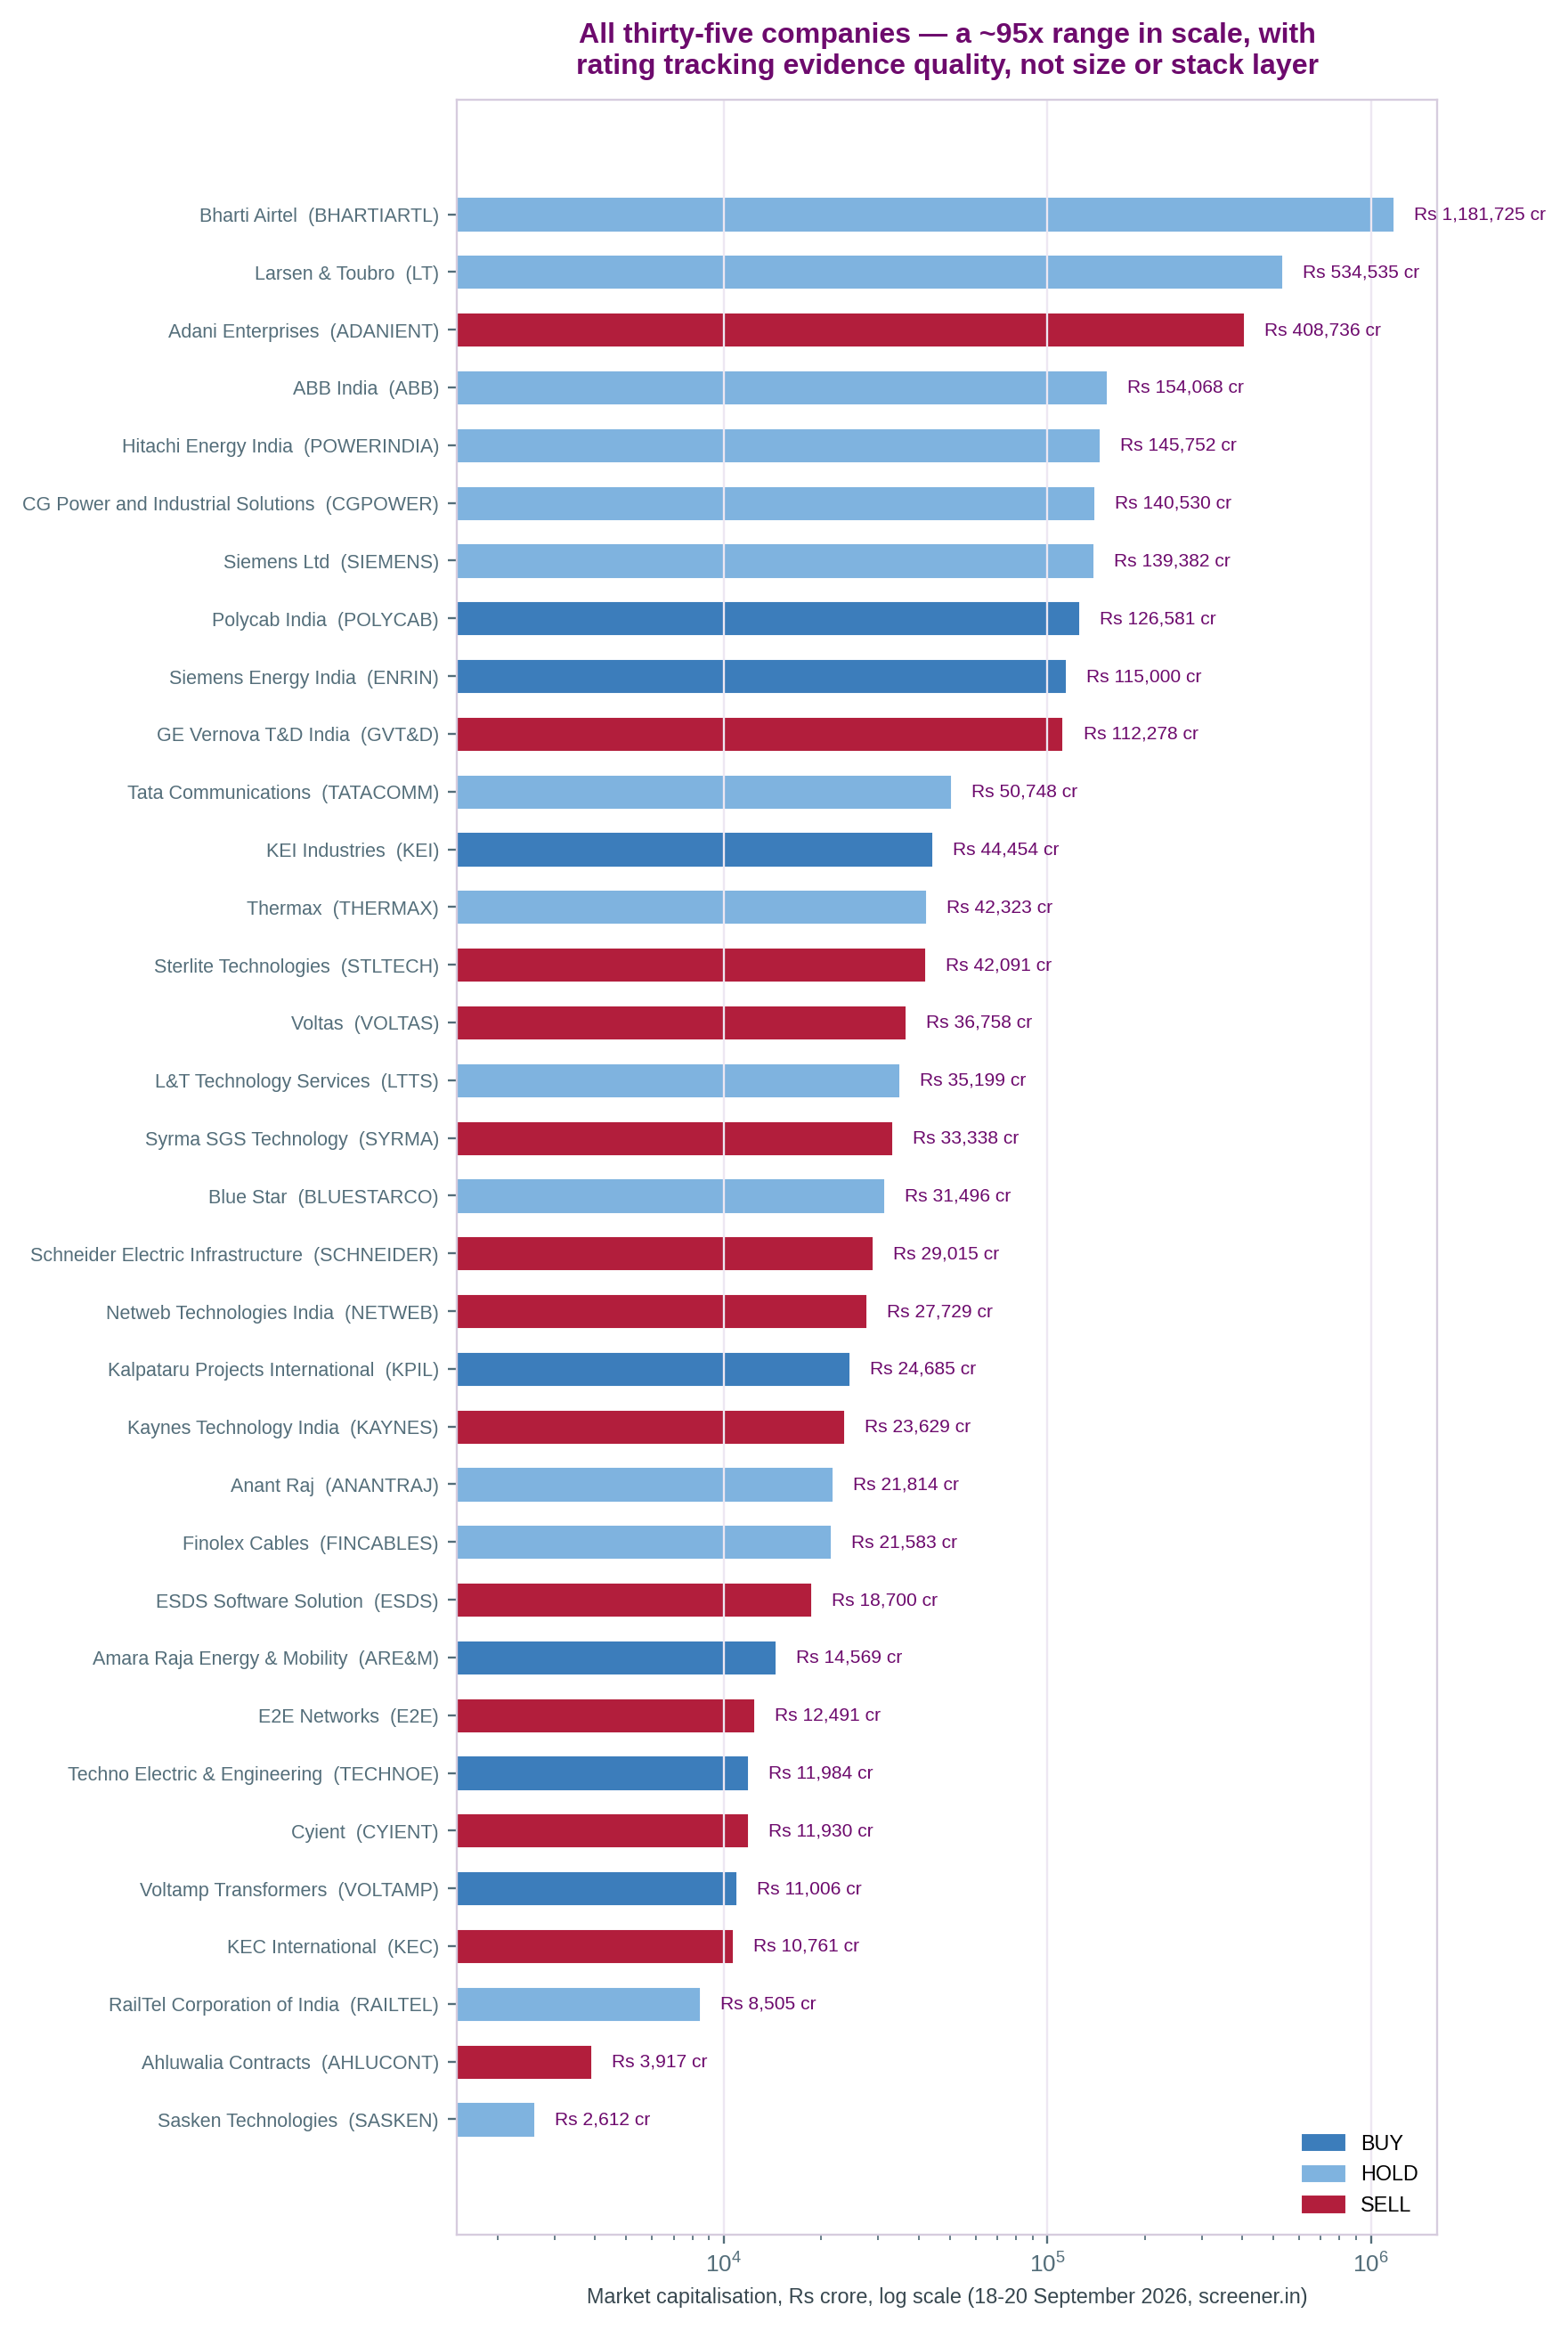
Ordered from the most upstream, abstract layer (chip design) to the most downstream/physical (civil construction), with GPU-cloud consumption and diluted telecom/conglomerate exposure — which sit adjacent to, not stacked within, the core physical chain — placed last.
| Layer | Companies (rating) |
|---|---|
| 1. Chip / IP design services | L&T Technology Services (HOLD), Cyient (SELL), Sasken Technologies (HOLD) |
| 2. Semiconductor packaging (OSAT) | Kaynes Technology (SELL), CG Power and Industrial Solutions (HOLD) |
| 3. Server / AI-hardware assembly | Netweb Technologies (SELL), Dixon Technologies (BUY), Syrma SGS Technology (SELL) |
| 4. Power equipment (transformers, switchgear, grid tech) | Voltamp Transformers (BUY), Hitachi Energy India (HOLD), ABB India (HOLD), GE Vernova T&D India (SELL), Siemens Ltd (HOLD), Siemens Energy India (BUY), Schneider Electric Infrastructure (SELL) |
| 5. Backup power / batteries | Amara Raja Energy & Mobility (BUY) |
| 6. Cooling | Blue Star (HOLD), Voltas (SELL), Thermax (HOLD) |
| 7. Cabling | Sterlite Technologies (SELL), Polycab India (BUY), KEI Industries (BUY), Finolex Cables (HOLD) |
| 8. Civil / EPC construction | Techno Electric & Engineering (BUY), KEC International (SELL), Kalpataru Projects International (BUY), Ahluwalia Contracts (SELL) |
| 9. GPU cloud / compute consumption | E2E Networks (SELL), ESDS Software Solution (SELL) |
| 10. Data-centre-adjacent telecom & conglomerates (diluted exposure) | RailTel (HOLD), Anant Raj (HOLD), Bharti Airtel (HOLD), Tata Communications (HOLD), Adani Enterprises (SELL), Larsen & Toubro (HOLD) |
Source: Dart Consultants, from each company's own report in Part 4. Layer 10 exists as its own category specifically because six companies here share the same structural pattern (§8, finding 4): real, disclosed data-centre exposure that does not meaningfully move the parent's own investment case.
A company where AI/data-centre work is the entire identity is not automatically the better investment — layers 3 and 8 above both show real businesses whose core economics (thin, compressing margin) the industry's own data confirms, regardless of growth headlines. A company in layer 10 is not automatically a bad investment either — several (Bharti Airtel, Tata Communications, L&T) carry real, separately-justified investment cases — but none is a data-centre bet in any way that matters to its valuation today. Read every rating in §11 against which layer, above, a company actually sits in.
Kaynes Technology carries a confirmed SEBI settlement order (27 March 2026, ₹23.42 lakh) against its promoter for insider-trading/database lapses, alongside a FY26 revenue miss with negative operating cash flow. CG Power's 2019 accounting-fraud episode predates the 2020 Murugappa Group takeover entirely but remains disclosure-relevant. Cyient's AI-compute exposure is still mostly a plan — the $218m TAO Digital acquisition had not closed as of this report's research date. ESDS Software Solution is a ~2-week-old listing already under exchange ASM Stage-1 surveillance, built almost entirely on one disclosed contract with an unverified counterparty. Anant Raj had its Delhi office searched by the Enforcement Directorate on 24 April 2026 in a money-laundering case unresolved as of this report's research date. Adani Enterprises reported a Q1 FY27 consolidated net loss driven by a $275 million US OFAC sanctions settlement — the most serious governance/legal red flag in this report's entire universe. Sterlite Technologies' Q1 FY27 profit is reported three irreconcilable ways across sources (₹125cr, ₹197cr, and a ₹17cr loss) — a genuine data-integrity issue, not a governance one, but serious enough to dominate its own rating. None of this makes any of the seven stocks automatically uninvestable; each is exactly the kind of structural detail this report exists to surface. Full reports for all thirty-five companies — financials, governance assessment, SWOT, valuation and rating — follow this primer.
